Offset mortgages have become increasingly popular in recent years as a way to save money on mortgage repayments.
But how exactly does an offset home loan work, and what are the benefits of using one?
This guide was updated in September 2026 with reader questions from the MumsMoney community.
Essentially, an offset account is a savings account that is linked to your home loan.
The balance of the savings account is offset against the balance of your home loan, meaning that you only pay interest on the difference between the two.
In this article, we will explore the ins and outs of offset home loans, including how they can help you save money on your mortgage, and what you need to know before signing up for one.
Table of Contents
- What is an offset home loan?
- How does an offset home loan work?
- Benefits of an Offset Home Loan
- Disadvantages of an Offset Home Loan
- Which New Zealand banks have offset accounts?
- Frequently Asked Questions – Offset Mortgage
- Does an offset savings account still earn interest?
- Does an offset mortgage mean I’ll repay my mortgage faster?
- Can you link more than one account to an offset mortgage?
- A revolving credit loan and an offset mortgage sound the same. What’s the difference?
- Do I have access to my savings if I have an offset mortgage?
- Can you make lump sum repayments with an offset mortgage?
- Can I get an offset mortgage for an investment property?
- How We Use an Offset Mortgage
What is an offset home loan?
An offset home loan is a type of mortgage that allows borrowers to reduce the amount of interest they pay on their home loan by offsetting their savings against their loan balance.
Essentially, an offset account is a savings account that is linked to your home loan account.
The balance in your offset account is then subtracted from the balance of your home loan when interest is calculated, which means you only pay interest on the difference.
For example, if you have a home loan of $500,000 and an offset account with a balance of $100,000, you would only pay interest on $400,000 of your home loan.
This can result in significant savings over the life of your mortgage, as you will be paying less interest overall.
In New Zealand, the offset products from BNZ, Westpac and Kiwibank offset the full balance of your linked accounts, up to the size of the offset loan. (You might see “partial offset” mentioned in Australian content — that’s a different product setup and doesn’t really apply here.)
The key thing to understand is that the offset loan is usually just one portion of your mortgage. Most people fix the bulk of their loan and set up a smaller floating portion to offset. So you don’t need hundreds of thousands in savings. You size the offset portion to match the cash you actually hold.
How does an offset home loan work?
Essentially, an offset account is a transaction or savings account that is linked to your home loan.
The balance of this account is then offset against the balance of your home loan, reducing the amount of interest you pay.
For example, let’s say you have a home loan with a balance of $500,000 and an offset account with a balance of $50,000.
With an offset home loan, the interest charged on your home loan would only be calculated on the difference between the two balances ($500,000 – $50,000 = $450,000).
This means you would only pay interest on $450,000, rather than the total $500,000.
It’s important to note that an offset account doesn’t actually pay off any of your home loans. Instead, the balance of your offset account is used to reduce the amount of interest you pay on your home loan.
This means you can still access your savings in the offset account whenever you need them, while still benefiting from the interest savings.
You still make your normal repayments
This is the part that confuses a lot of people. Your repayment amount doesn’t change just because you have money in offset. The bank still sets your repayments as if you were paying the full floating rate.
The difference is where that money goes. If less interest is being charged, more of each repayment goes to the principal, so the loan shrinks faster. If the portion is 100% offset, the entire repayment goes to principal.
(There is a way around the repayments, which is going interest-only on a fully offset loan. More on that in the FAQs below.)
What “effective interest rate” means
You’ll often see offset users talk about their effective rate, and it can look too good to be true.
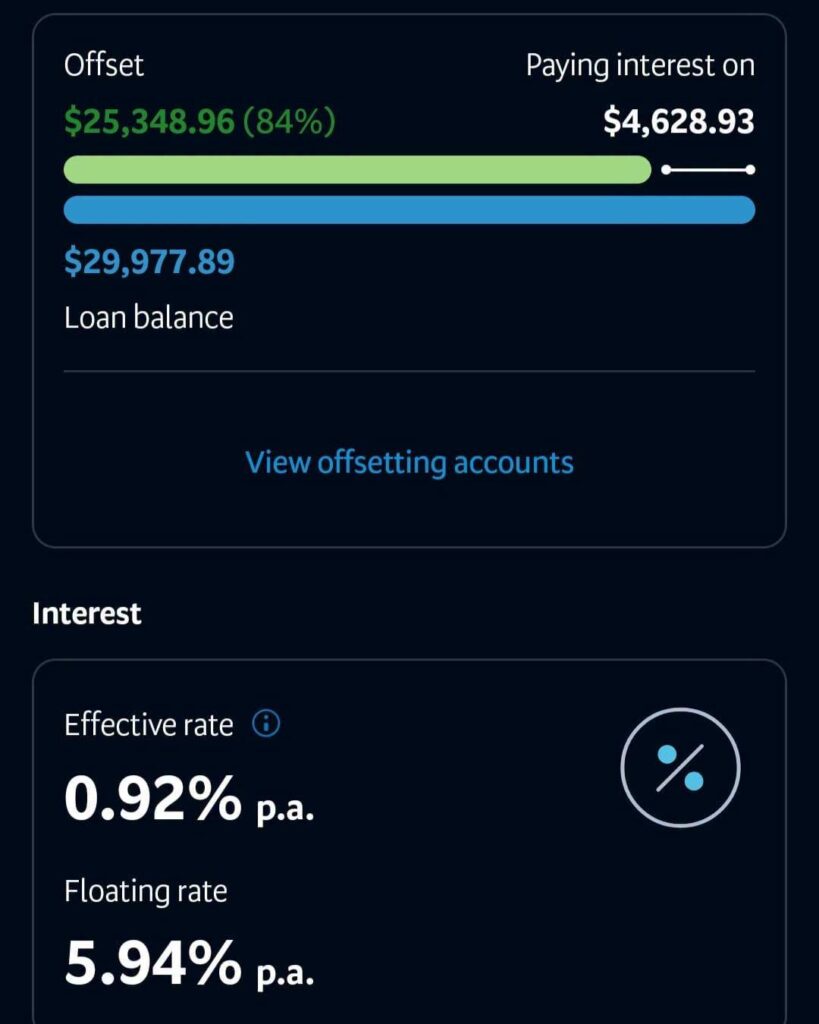
Here’s a real example from one of our loans (image above).
We had about 84% of a roughly $30,000 portion offset. The floating rate on that loan was 5.94%.
Because we were only being charged interest on the small un-offset slice, the effective rate across the whole portion worked out at 0.92%.
The bank didn’t give us a 0.92% rate. We were paying 5.94% on a much smaller balance, which works out the same as paying 0.92% on the whole thing.
If the portion is fully offset for the whole month, the effective rate is 0%.
Benefits of an Offset Home Loan
Saves Money on Interest Payments
Any money you have in your savings or transaction account will be offset against the balance of your home loan.
This means that the interest you pay on your home loan will be calculated on a reduced balance, which can save you money over the life of your loan.
For example, if you have a home loan balance of $500,000 and you have $50,000 in your linked savings account, the interest on your home loan will be calculated on a balance of $450,000.
This means you will pay less interest over the life of your loan than you would if you didn’t have an offset account.
Reduces the Loan Term
Because less interest is being charged, more of every repayment goes to the principal, and that shortens the life of the loan.
To put some numbers on it: on a $30,000 floating portion at 5.94%, you’d pay around $1,780 in interest a year. If that portion is fully offset, that $1,780 goes to principal instead, every year, without you paying a cent more than your normal repayment.
We used this exact approach (along with extra repayments) to pay off our previous home in five years.
Flexibility to Access Funds
The money in your offset accounts is still yours. It sits in ordinary accounts that you can spend from, transfer out of, or use for bills whenever you need to.
That’s the big difference compared with paying a lump sum off a fixed loan. Once extra money goes onto a fixed loan, it’s usually much harder to get back out.
With offset, you get most of the interest saving of paying the loan down, but you keep the cash on hand for emergencies, bills, or anything else life throws at you.
The trade-off is that spending from those accounts reduces the offset, so you’ll pay a bit more interest until the balance builds back up.
Disadvantages of an Offset Home Loan
Higher Interest rates
While offset accounts can save you money on interest payments, in New Zealand, they tend to come with higher interest rates than regular home loans.
This is because New Zealand offset mortgage options are all on floating interest rates, which are significantly higher than a fixed rate.
Always compare the interest rates of different offset home loans and ensure that the savings from the offset account outweigh the higher interest rate you pay for the privilege.
That said, the higher rate matters less than it looks.
The whole idea is that you don’t actually pay it on the offset portion. If the portion is fully or mostly offset, the headline floating rate barely touches you.
Where it does bite is if your savings drop and the portion sits mostly un-offset for months at a time. So only put on floating what your cash can realistically cover.
Fees and charges
Another factor to consider before getting an offset home loan is the fees and charges associated with the loan.
Offset home loans may come with higher fees and charges than regular home loans, including annual fees, establishment fees, and ongoing fees.
Make sure to compare the monthly fees and charges of different offset home loans and ensure that the savings from the offset account outweigh the higher fees and charges.
In our case, the bank charges $10 each month for the Total Money offset facility but they reimburse it to us immediately (as part of a loyalty package).
Eligibility requirements
It is essential to ensure that you meet the eligibility requirements before applying for an offset home loan.
Some lenders may require a minimum deposit or minimum balance in the offset account and may have other eligibility requirements.
Is an offset account worth it with only a small amount of savings?
It can be. There’s a common idea that offset only works if you’ve got a big pile of cash, but that’s only true if you set the offset portion up too large.
Some real examples from MumsMoney readers:
- A $15,000 loan portion (originally taken out for a car) that’s now paying zero interest on the $6,500 remaining
- A couple in their 50s who started with a $10,000 offset portion as a trial
- Our own offset portion, which sits at around $30,000
The rule of thumb is to match the offset portion to the cash you reliably hold throughout the year.
Think about everyday spending money, bill accounts, sinking funds, and your emergency fund. Fix the rest of the loan as normal.
Where offset doesn’t work well is if your accounts are regularly close to empty. Then you’re just paying the floating rate on that portion for no benefit.
Offset or invest? What money belongs in offset
A fair question we get is: why not invest the money instead?
For long-term money, that’s often the right call. Diversified investments have historically returned more than mortgage interest rates over long periods, though with ups and downs along the way.
But offset isn’t meant for long-term investment money. It’s for money that has to be held somewhere anyway:
- Your emergency fund
- Sinking funds (car, Christmas, holidays, rates, insurance)
- Money set aside for tax, GST or ACC
- Everyday spending and bill accounts
That money needs to be safe and instantly available, so it can’t sensibly be invested. The real comparison is offset vs a savings account, and offset usually wins.
Here’s a simple example with $10,000 (the rates are illustrative, so use your own):
| Savings account at 3% | Offset against a 5.94% loan | |
|---|---|---|
| Interest earned / saved | $300 | $594 |
| Tax | Around $90 (at a 30% tax rate) | $0 |
| You’re better off by | $210 | $594 |
Because you’re saving interest rather than earning it, there’s no tax to pay. That’s what makes offset so effective for cash you need to keep on hand.
This is general information, not personal financial advice. How to split your money between offset and investing depends on your situation, so talk to a financial adviser if you’re unsure.
Which New Zealand banks have offset accounts?
BNZ, Westpac and Kiwibank all offer offset mortgages.
| 100% offset allowed | Maximum linked accounts | Monthly fee | Establishment fee | |
| BNZ Total Money | Yes | 50 | $10 | yes |
| Westpac Choices | Yes | 10 | $5 | yes |
| Kiwibank Offset | Yes | 8 | none | yes |
What if my bank doesn’t offer offset?
ANZ and ASB don’t currently offer offset mortgages in New Zealand. If you bank with them, your main options are:
- Revolving credit. This works in a similar way (see the FAQ below on the difference).
- Switching banks. Do this at the end of a fixed term to avoid break fees, and ask whether the new bank will cover legal costs.
- Saving towards refix time. Build up cash in a separate account and put it on the loan when your fixed term ends.
Frequently Asked Questions – Offset Mortgage
Does an offset savings account still earn interest?
No. In New Zealand, accounts linked to an offset mortgage don’t earn interest.
Instead, the bank subtracts your savings from the loan balance before calculating interest. If you owe $100,000 and have $5,000 in offset, you’re charged interest on $95,000.
That’s usually a better deal than earning interest. You’re effectively getting a return equal to your mortgage rate, and because you never earn the interest, you don’t pay tax on it. A savings account paying 3% is really paying less than that once tax comes off. (See the worked example above.)
Does an offset mortgage mean I’ll repay my mortgage faster?
An offset mortgage has the potential to help you repay your mortgage faster, but this will depend on the structure of the mortgage and how you use the offset account.
The main benefit of an offset mortgage is that the balance of your savings account is offset against the balance of your mortgage.
This means that you only pay interest on the difference between your mortgage balance and your savings balance.
By reducing the amount of interest charged on your mortgage, an offset mortgage can help you reduce the overall amount of interest you pay over the life of the loan.
If you continue to make your regular mortgage payments but use your offset account to hold your savings and reduce the amount of interest charged on your mortgage, you may be able to repay your mortgage faster than you would with a traditional mortgage as more of the monthly repayment will be going towards paying the principal and increasing your equity.
Can you link more than one account to an offset mortgage?
Yes, it is possible to link more than one account to an offset mortgage in New Zealand.
BNZ allows you to link up to fifty accounts. Westpac allows ten linked accounts, and Kiwibank allows eight.
This may be useful if you have multiple savings accounts that you want to use to offset your mortgage balance.
For example, if you use multiple accounts to budget, you can link them to your offset mortgage.
In my case, my and the husband’s splurge money accounts, our children’s pocket money accounts, our grocery account, travel savings, bills account, all the sinking funds and cash savings accounts (emergency fund etc.) all offset against the mortgage for one of our rental properties (we’ve already paid off our own home).
A revolving credit loan and an offset mortgage sound the same. What’s the difference?
They save interest in the same basic way, because your spare cash reduces the balance you’re charged interest on.
The difference is in how they’re set up.
Revolving credit is one big account that works like an overdraft with a limit. Your pay goes in, and your spending comes out of the same account. The balance (and the interest) goes up and down with your spending. Some banks reduce the limit over time (often called “reducing revolving credit”).
An offset mortgage keeps the loan and your savings separate. The loan has set repayments and only goes down. Your money sits in ordinary linked accounts, and the bank adds up their balances and subtracts them from the loan when calculating interest.
In practice, the main differences are:
- Budgeting. Offset lets you keep lots of separate accounts (groceries, bills, sinking funds), which suits anyone who budgets with multiple bank accounts (like me with my zero sum budget). Revolving credit tends to lump everything into one account.
- Discipline. Revolving credit is easy to spend against, because it looks like a giant overdraft. Offset keeps the loan and your spending money visibly separate.
- Family. Some offset products let family members link their accounts (see below). Revolving credit doesn’t.
Neither is better for everyone. If you’re disciplined and like one simple account, revolving credit can work well. Plenty of people have paid off their mortgage with it.
Do I have access to my savings if I have an offset mortgage?
Yes, with an offset mortgage, you have access to your savings as they are held in a linked savings account that is offset against your mortgage balance.
While the savings are used to offset the interest charged on your mortgage, they are still considered your own funds and can be accessed as needed.
However, remember withdrawing funds from your linked savings account may reduce the amount of offset against your mortgage balance and increase the amount of interest charged on your mortgage.
Can you make lump sum repayments with an offset mortgage?
Yes, in most cases, you can make lump sum repayments on an offset mortgage.
The availability and terms of making lump sum payments may vary depending on the lender and the specific offset mortgage product.
Typically, New Zealand offset mortgages allow borrowers to make additional payments towards their mortgage balance as they are mostly a floating home loan option, which tends to allow extra repayments without penalty.
Some lenders may have specific rules or limitations around lump sum payments, such as minimum and maximum amounts or frequency of payments.
Can I get an offset mortgage for an investment property?
Yes, it is possible to get an offset mortgage for an investment property in New Zealand.
While offset mortgages are most commonly associated with owner-occupied properties, some lenders do offer offset mortgages for investment properties as well.
However, it’s worth noting that the availability and terms of offset mortgages for investment properties may be different from those for owner-occupied properties.
For example, some lenders may require a higher deposit or equity threshold for investment properties or may charge higher interest rates or fees.
Shop around and compare different lenders and mortgage products to find the one that best meets your needs.
Mortgage brokers will be able to do much of the hard work for you, so definitely seek out one near you.
Speak with an accountant or financial adviser to understand how an offset mortgage on an investment property may impact your tax situation.
How We Use an Offset Mortgage
I’m adding a quick case study of how we use an offset home loan for reference. The screenshots below are my own.
Before I start, I want to clarify two things:
- We currently use an offset account on an investment property home loan.
- We used the EXACT same strategy on our OWN home to pay that mortgage off in five years.
We’ve been using an offset mortgage (BNZ Total Money) for as long as the option has been available.
I’ve always been very interested in making every dollar work as hard as it possibly could for us.
When we came back to live in New Zealand, that became even more vital as our earning power reduced. We structured our home loan with a fixed portion and a floating (offset) portion.
We’ve never had a complete home loan as an offset, as we’ve never held that much cash in savings.
For example, this might mean having $200,000 across various fixed rates and $30,000 on offset.
We estimate how much cash savings we can hold during a year and maintain an offset balance around that amount – currently just under $30,000.
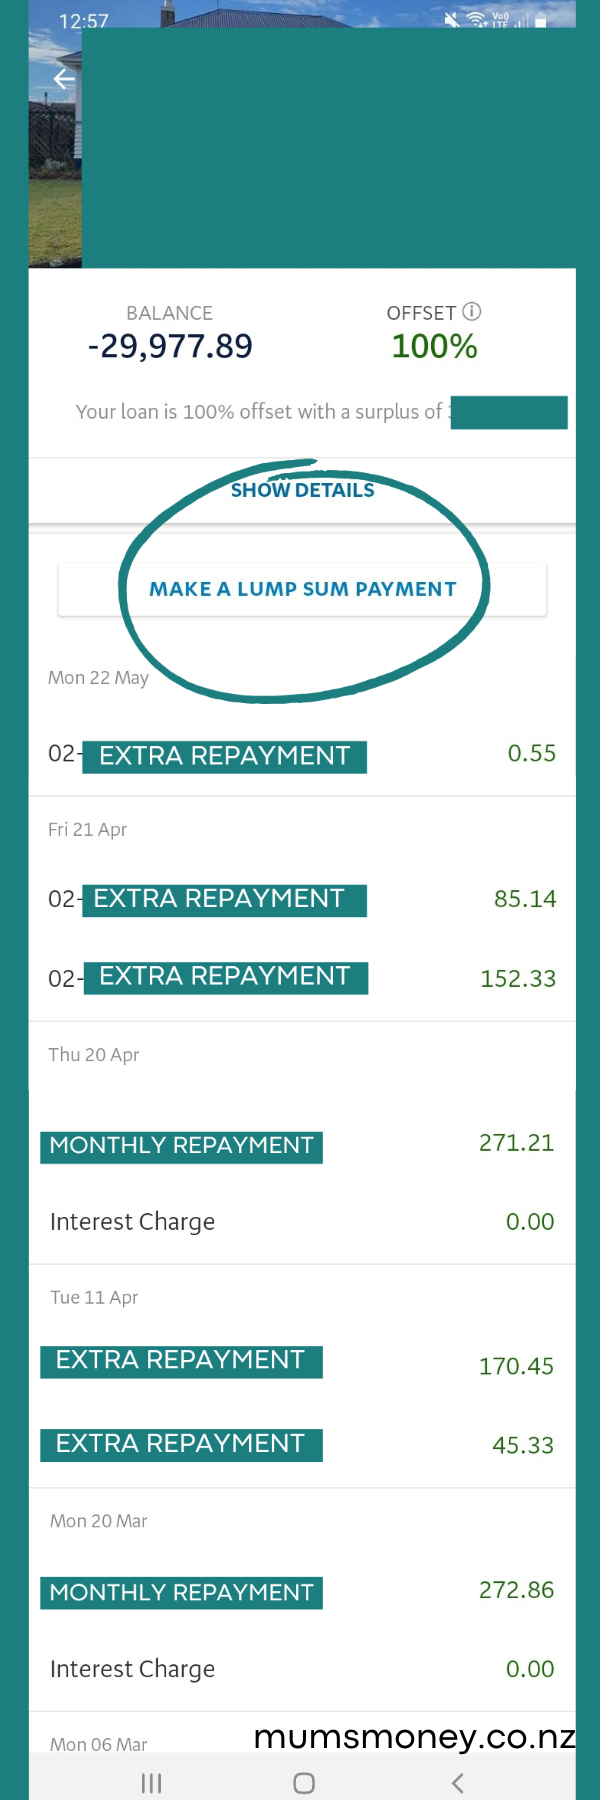
Our goal is to pay no interest at all.
We do that by offsetting 100% of the loan with our savings.
This means that the entire monthly payment goes to the principal – reducing the loan balance.
Being a floating loan means we can and do make extra lump sum repayments as frequently as we can with no penalty. Even when the extra repayment is $0.55 – every little bit helps!
When we eventually pay this loan off totally, we will switch a portion of another loan to offset so we always have an offset facility to avail of until we are completely debt free.
So that’s how we use an offset account to optimise our finances for maximum debt reduction.
Do you use an offset account? Do you have any tips to add?